Women’s retirement gap shrinks but poverty risks persist
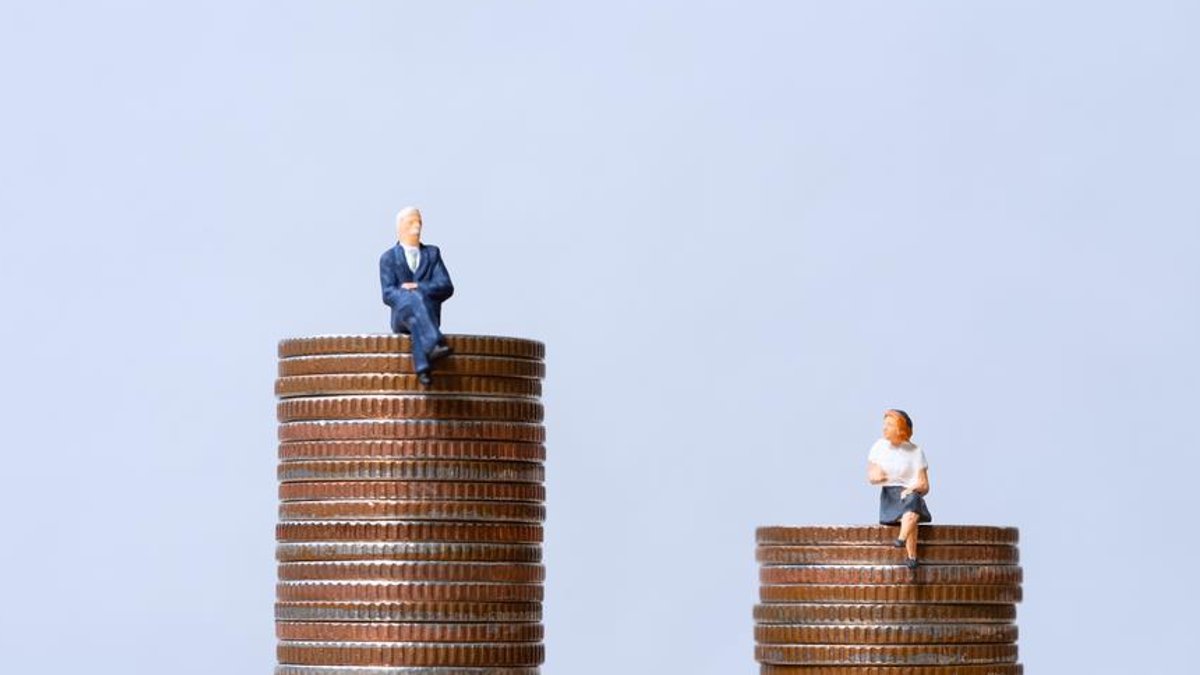
The latest Scottish Widows Women and Retirement Report shows the annual difference between men’s and women’s projected retirement incomes has shrunk to £3,800, down from £6,000 in 2025 and £7,000 in 2023. Women now expect a median retirement income of £14,500 yearly, an increase of £1,500 from earlier projections, while men’s remains at £18,300. This reduction in the gap stems from narrower pay disparities, higher state pension entitlements, and greater private savings among women.
Despite this progress, a significant gap remains in defined contribution pension pots, with women averaging £95,000 less than men. The report highlights that 65% of women are on track for only a basic retirement standard, and one-third risk poverty in later life. Just 27% are projected to achieve a comfortable retirement.
Care responsibilities and financial setbacks
Women who balance unpaid caring duties face substantial financial penalties. Those working part-time to support adult dependents could collectively forfeit £220 million in annual pension contributions, the report estimates. Among carers, 27% took time away from work due to unaffordable childcare, while 14% reduced their working hours.
Debbie Sheffield, relationship director at Scottish Widows, observed that the financial impact of unpaid care often remains hidden until later stages. She noted, “Employers may look at pension participation, contribution rates or engagement data to understand how their people are doing. But carers may not stand out. They may still be working and contributing, but may have reduced their hours, taken unpaid leave, stepped into a lower-paid role or missed opportunities for progression.”
Other life events further disrupt retirement planning. Almost three in 10 (29%) women managing menopause symptoms reported a negative impact on their retirement savings, while 25% of divorced women said their retirement preparation had worsened. Pensions were not discussed during 24% of separations, and only 16% of divorces involved pension sharing or offsetting in financial settlements.
Young women and automatic enrolment barriers
Data from Lloyds Banking Group customers reveals that 14% of women under 30 earn below the £10,000 automatic enrolment threshold, compared with 9% of men. This exclusion from workplace pension schemes early in their careers worsens long-term savings disparities.
Low awareness of National Insurance credits also contributes to the problem. Only 39% of women providing regular adult care had heard of these credits, which help protect state pension entitlements, while just 11% had claimed or received them.
Policy and workplace reforms required
Scottish Widows urged employers to use workforce and pension data to identify differences in participation and contributions by gender, age, earnings and working patterns. It recommended that changes – such as parental leave, reduced hours, and returning to work – trigger support to help employees understand and rebuild their pension savings. The report also highlighted low awareness of National Insurance credits and recommended stronger financial education for younger workers. It encouraged couples to share caring responsibilities and plan for retirement together while protecting individual financial independence. From pension enrolment and parental leave to support through divorce, menopause and illness, policy and workplace changes must better reflect women’s lives and help them build financial security at every stage.

Related Articles


 Green Certifications